How Fixed Indemnity Plans Can Help Cover Your Deductible on a Colorado Bronze Plan
Bronze plans have the lowest premiums on the Marketplace. The trade-off is a big deductible, often several thousand dollars, that you pay before the plan starts sharing costs.
For a lot of people, that’s the scary part. You save money every month, then one ER visit or hospital stay wipes out your savings account.
A fixed indemnity plan is one way to soften that hit. In this post, we’ll explain what it is, walk through a real-dollar example year, and help you decide whether it’s worth the extra premium for you.
What Is a Fixed Indemnity Plan?
A fixed indemnity plan pays you a set dollar amount when a covered event happens, no matter how much the bill is.
For example, a plan might pay:
- A flat amount for each day you’re in the hospital
- A flat amount for an emergency room visit
- A smaller flat amount for each doctor visit
The money usually goes straight to you, not the hospital. You can use it for your deductible, your copays, your rent or anything else.
What it isn’t: full health insurance. It doesn’t cover your whole bill, it doesn’t have an out-of-pocket max, and it doesn’t replace a Marketplace plan. Think of it as a sidekick: your Marketplace plan protects you from a catastrophic year, and the fixed indemnity plan helps with the deductible you pay on the way there.
An Example Year: Bronze Plan + Fixed Indemnity
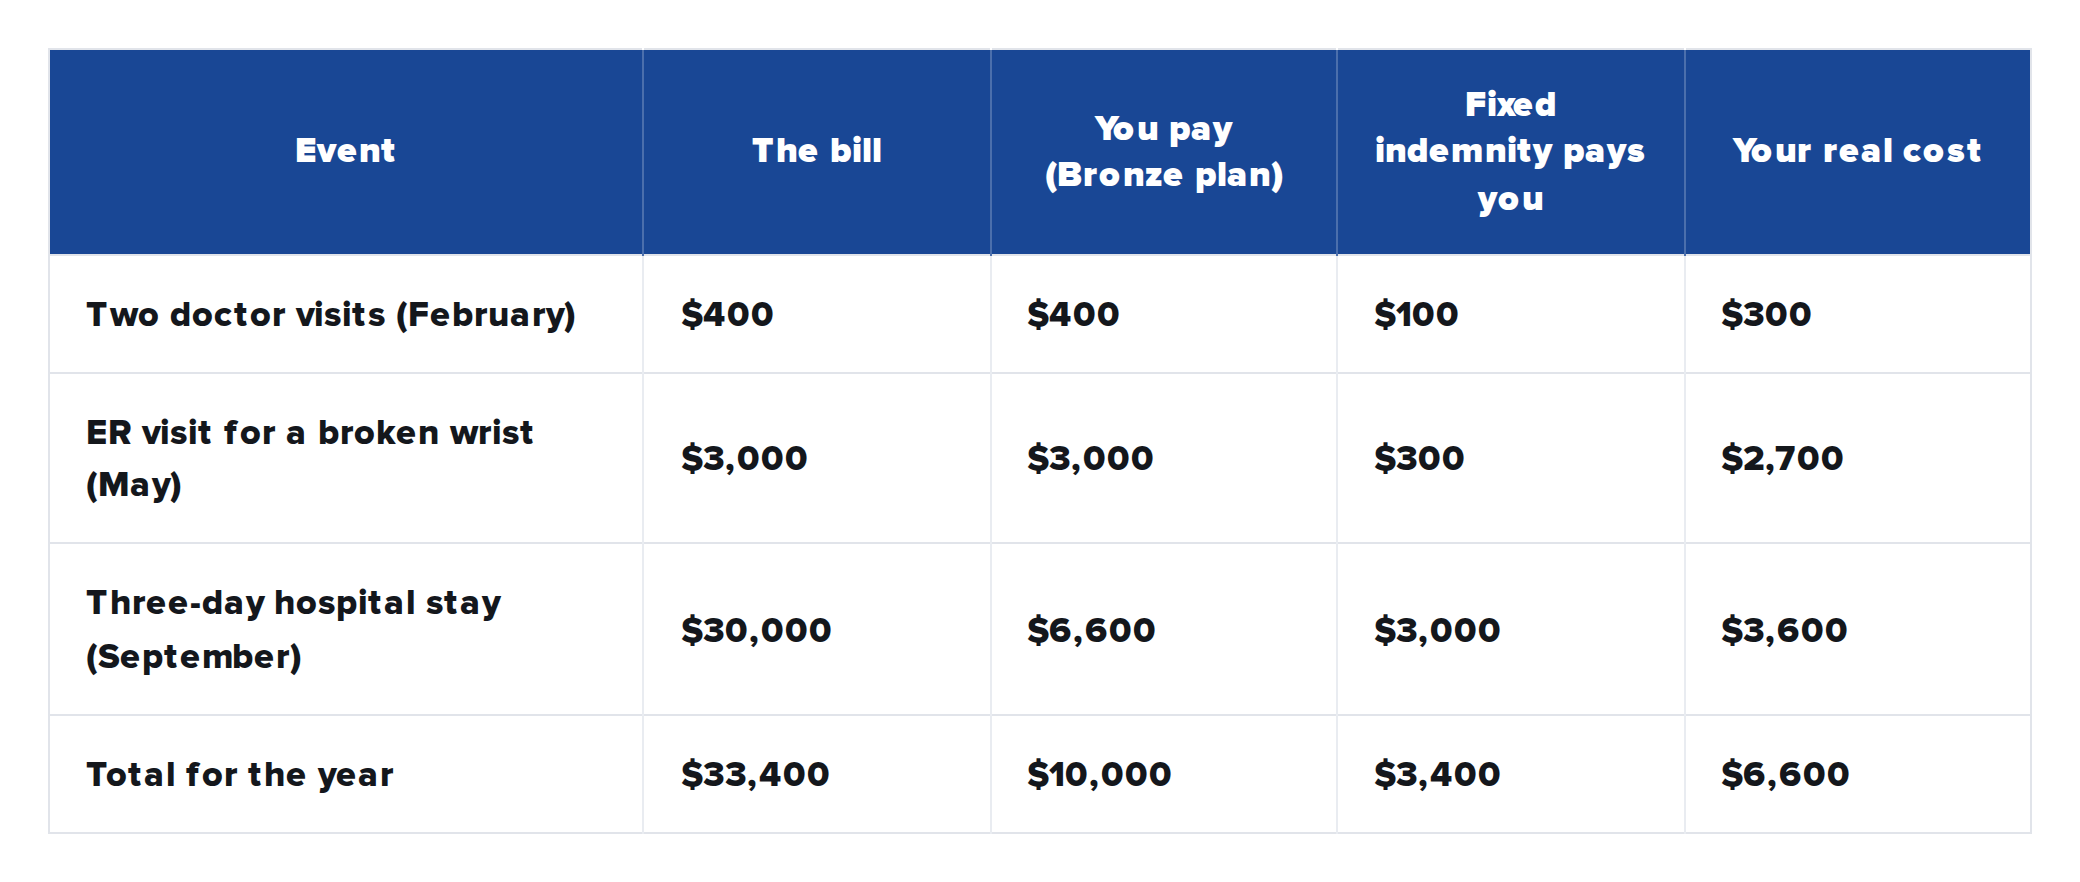
Here’s how the two plans work together. These are example numbers, not a specific plan.
The Bronze plan: $7,500 deductible, 40% coinsurance after that, and a $10,000 out-of-pocket max.
The fixed indemnity plan pays: $50 per doctor visit, $300 per ER visit and $1,000 per hospital day.
A few things to notice:
- Before the hospital stay, you’d paid $3,400 toward your deductible. The fixed indemnity plan gave $400 of that back.
- The hospital stay hit the Bronze plan’s out-of-pocket max, so your share stopped at $6,600. The fixed indemnity plan paid $3,000 on top of that, because it pays per day no matter what your other plan covers.
- For the year, the fixed indemnity plan cut your $10,000 worst case down to $6,600.
Does It Actually Pay Off?
A fixed indemnity plan has its own monthly premium. Say it costs $60 a month, or $720 a year (again, an example).
In the example year above: you paid $720 and got $3,400 back. You came out $2,680 ahead.
In a quiet year with just two doctor visits: you paid $720 and got $100 back. You came out $620 behind.
That’s how all insurance works: you pay a little every month so a bad year hurts less. The real question is whether that trade is worth it for you. It usually makes the most sense when:
- A surprise $3,000 to $7,000 bill would be hard to cover from savings
- You’re choosing Bronze mainly to keep your premium low
- Your household is active, has kids, or has a reason to expect an ER visit or two
If you could comfortably pay your whole deductible from savings, you may be better off putting that $60 a month into an HSA instead.
What to Check Before You Buy
Fixed indemnity plans vary a lot. Before you buy one, look at:
- What it pays for each event. Check the amounts for the things you’re most likely to use: doctor visits, ER visits, hospital days, outpatient surgery.
- The limits. Many plans cap how many days or visits they’ll pay for, or how much they’ll pay in a year.
- Waiting periods and pre-existing conditions. Some plans won’t pay for certain conditions right away, or at all.
- How claims work. Find out how you file and how quickly you get paid.
- That you’re keeping real coverage. A fixed indemnity plan should sit next to a Marketplace plan, not replace it. Without the Marketplace plan, there’s no out-of-pocket max protecting you from a $100,000 year.
Who It’s Best For (and Who Should Skip It)
A good fit for:
- People on a Bronze plan who want a low premium without a scary deductible
- Families with active kids
- Freelancers and self-employed people without a big emergency fund
- Anyone earning too much for tax credits who’s looking to lower their total costs
Probably skip it if:
- You’re on a Gold plan with a low deductible already
- You have enough savings to cover your full deductible comfortably
- You’d be buying it instead of a Marketplace plan
The bottom line
A fixed indemnity plan won’t replace health insurance, but paired with a Bronze plan, it can turn a scary deductible into a manageable one. The key is matching the right plan to how your household actually uses care.
This is one of our specialties. We’ll compare Marketplace plans with and without fixed indemnity, show you the full-year math for a quiet year and a rough one, and help you pick what fits.
Book a free call or call 303-225-0073. It’s always free to work with us.