Buying Your Own Health Insurance as a Ski Town Worker in Colorado
If you work in Steamboat or another mountain town, you know the rhythm. Winter is packed. Mud season is quiet. Summer brings a different job, or no job at all.
That rhythm makes health insurance harder. Your income swings, your job coverage may end when the lifts close, and there are fewer doctors and plans to choose from than on the Front Range.
Here’s what to know about seasonal income, smaller networks and the steps to take before the season starts.
Seasonal Income: Estimate the Whole Year
When you apply through Connect for Health Colorado, your tax credit is based on what you expect to earn for the whole year, not what’s in your paycheck right now.
The mistake we see most often: someone applies in December and multiplies their winter paycheck by 12. That number is too high, and it can shrink or wipe out the help they qualify for.
Instead, add up each piece of your year:
- Your winter job, including tips
- Your summer or shoulder-season work
- Anything else, like unemployment between seasons, a side gig or a partner’s income
Here’s an example. Say you’re single and work as a lift operator in Steamboat, then guide raft trips in the summer:
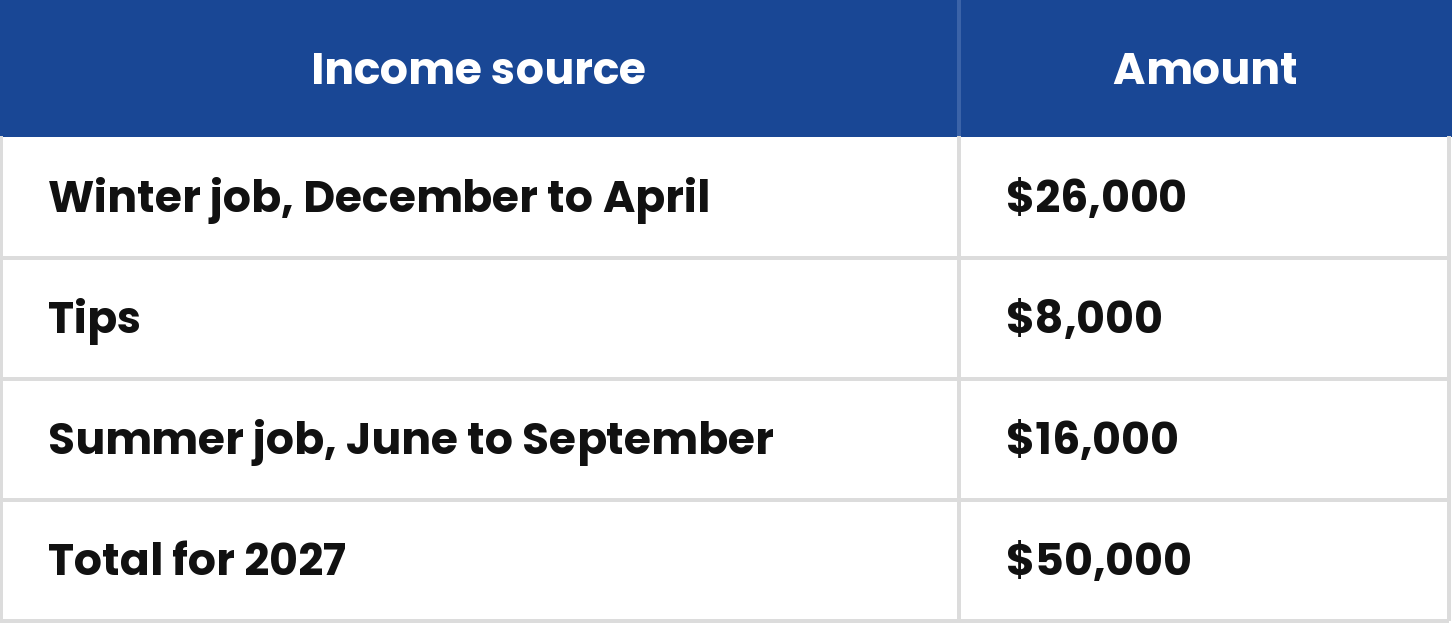
That’s under the 2027 tax credit limit of about $63,840 for one person. If this worker had multiplied a winter month, about $6,800 with tips, by 12, they would have guessed $81,600. That’s over the limit, so they’d be told they get no help at all. (These are example numbers. Yours will be different.)
Update your income when it changes. Got more hours, lost your summer job, or started a new one? Log in to Connect for Health Colorado and update it within 30 days. That keeps your tax credit accurate and your tax-time surprise small.
In a slow month, check Health First Colorado. Colorado’s Medicaid program is free or low cost and you can apply any time of year. For seasonal workers, it can look at your monthly income or average it across the year, so it’s worth checking if your income drops off between seasons.
Smaller Networks: Check Before You Pick
In Denver, you can choose from many insurers. In the mountains, the list is much shorter. For 2027, only four insurers sell plans in the state’s western region, and not every one covers every county. Premiums there are rising about 11.8% on average.
Most plans here are HMOs. That means the plan only pays for doctors and hospitals in its network, except in an emergency. If your doctor isn’t in the network, you pay the full bill.
Before you pick a plan, check that it includes:
- Your local hospital. In Steamboat, that’s UCHealth Yampa Valley Medical Center. In Aspen, it’s Aspen Valley Health. In Breckenridge, Keystone and Copper, it’s St. Anthony Summit Hospital in Frisco. In Vail, it’s Vail Health Hospital.
- Your doctors. Search each name in the plan’s provider directory, then call the office to confirm.
- Specialists you might need. If you’d drive to Denver or Grand Junction for an orthopedic surgeon or other specialist, make sure they’re in the network too.
- Your prescriptions. Look up each one in the plan’s drug list.
Emergencies are covered anywhere. If you’re hurt on the mountain and taken to the nearest ER, your plan has to cover it like in-network care, even if that hospital isn’t in your network. Follow-up visits and surgery that can wait are different, so get those in-network.
What to Know Before Winter
Know the dates. Open Enrollment for 2027 runs November 1, 2026 to January 15, 2027. Sign up by December 15 for coverage that starts January 1. If you sign up later, coverage starts February 1, which leaves you without coverage during the busiest weeks on the mountain.
Ask about your job’s health plan. If you’re working for a resort or a larger employer this winter, ask HR:
- Does my position qualify for the health plan?
- When does coverage start, and when does it end?
- What will it cost me each month?
If your employer offers you a plan that’s considered affordable, you generally can’t get tax credits on a Marketplace plan. Find out before you enroll.
Plan for when the season ends. Losing job-based coverage gives you 60 days to sign up for a Marketplace plan. Mark the date your coverage ends, and apply before it does so there’s no gap.
Don’t just let your plan renew. If you have a plan now, you’ll be automatically re-enrolled, but your price, tax credit and network may have changed for 2027. Log in, update your income and compare.
The bottom line
Estimate your income for the whole year, not your best month. Check that your hospital and doctors are in the network before you pick a plan. And sign up by December 15 so you’re covered when the season starts.
We help ski town workers in Steamboat and across the mountains every year. We’ll build your income estimate, check networks for your doctors and plan around your job’s coverage, so you’re set before the first chair.
Book a free call or call 303-225-0073. It’s always free to work with us.